Car Insurance Add Ons Worth It: Which Ones to Buy and Skip in 2026
 By Anjani ChaandOctober 14, 20267 min read
Key Takeaways
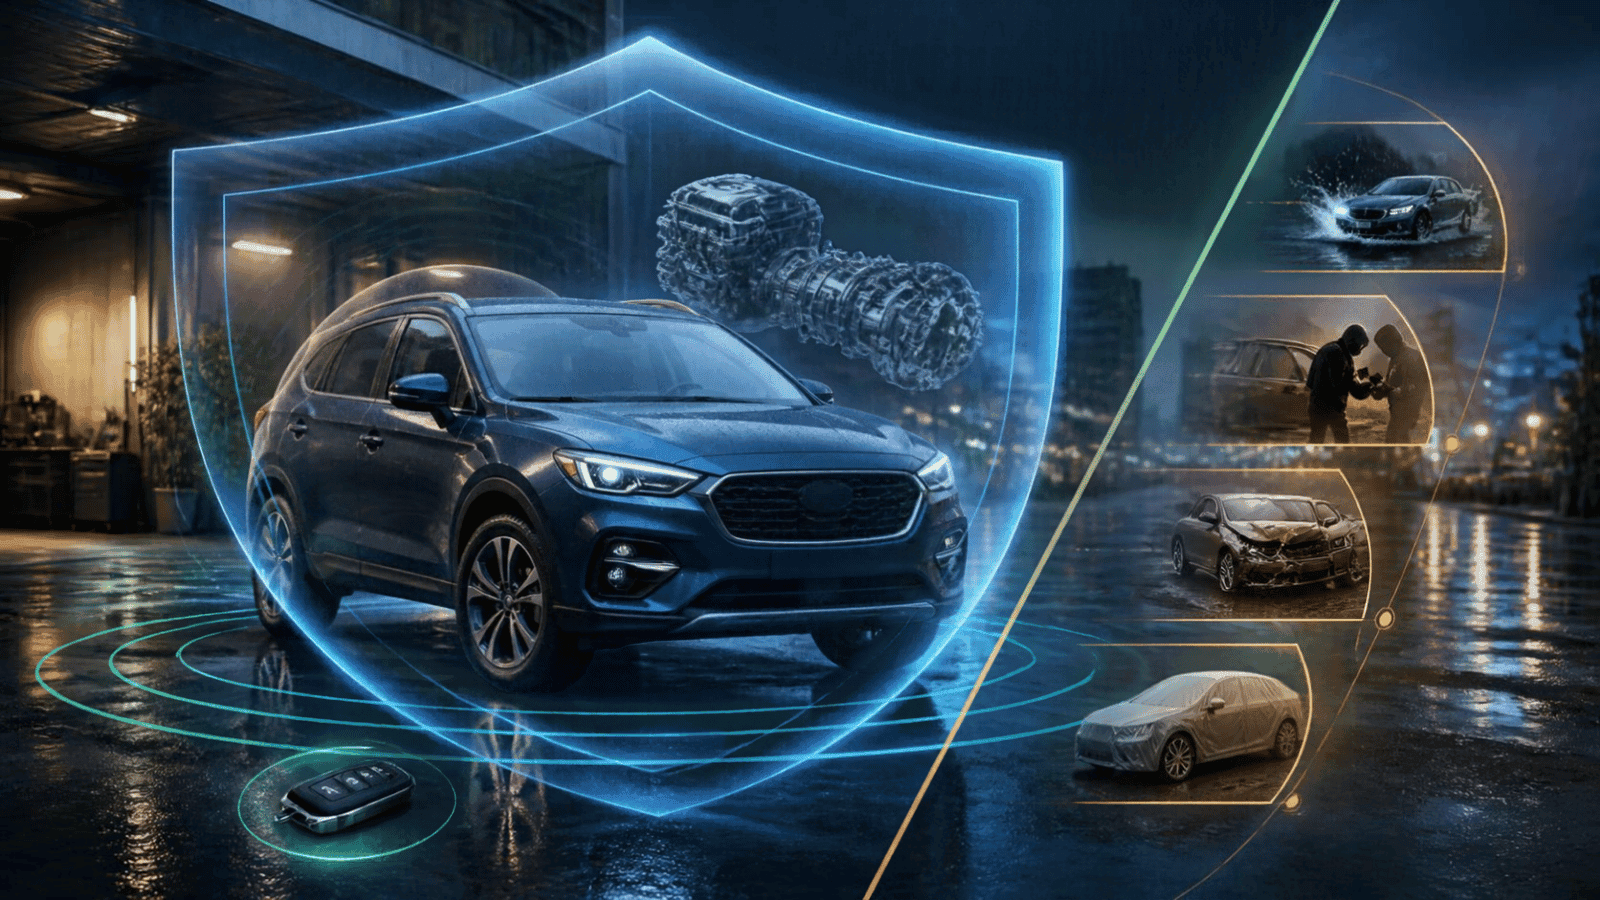
- Zero Depreciation, Engine Protection and Return to Invoice are some of the most cost-effective car insurance add-ons worth it. While Zero Depreciation covers depreciation deductions on replaced parts during partial damage or accidental repairs, Engine Protect provides coverage against engine and gearbox damage caused by water ingress, hydrostatic lock, or oil leakage. An RTI bridges the gap between the car’s IDV and the original invoice price, inclusive of registration and road taxes, in case of total loss or theft.
- Insurers offer specific add-on features on top of your standard comprehensive or own damage car insurance policies. Purchasing these add-ons requires paying 10-20% extra above your annual premiums.
- Individuals who have access to an alternative transport option while their car is undergoing repairs at the workshop can skip the Daily Conveyance add-on cover.
- A Key and Lock Set Replacement cover makes sense for buyers owning a specialized key and lock fobs worth ₹20,000 or more.
Are Car Insurance Add Ons Worth It for Indian Buyers?
Car insurance add-ons are worth buying because a standard car insurance policy covers only part of repair bills, as insurers deduct the vehicle’s depreciated value from replacement parts and exclude natural wear and tear.
Under IRDAI regulations, standard claims deduct 50% depreciation from plastic, rubber, nylon, paint, and battery parts. 10-50% is deducted on metal body panels based on the vehicle’s age. Car insurance add-ons bridge this financial gap by covering out-of-pocket expenses. Some add-on riders worth buying include Zero Depreciation, Engine Protect, and Return to Invoice (RTI) covers. To include these on top of your regular comprehensive or own damage policy, you must pay a slightly higher premium. But in return, you get broader protection without overspending on your annual car insurance policy.
Check our detailed guide on Comprehensive vs Third-party car insurance for first-time buyers.
Key Car Insurance Add Ons Worth Buying vs Skipping
| Add-On Cover Name | Average Cost (% of Regular Policy Premium) | Primary Claim Coverage Benefit | Verdict |
| Zero Depreciation | 10%–20% | Eliminates mandatory 50% plastic/rubber and graduated metal depreciation deductions | Essential for cars up to 5 years old |
| Engine & Gearbox Protection | 5%–10% | Covers internal engine hydrostatic lock, oil starvation, and gearbox repairs | Essential for flood-prone cities/monsoon driving |
| Return to Invoice (RTI) | 10%–15% | Reimburses full original invoice price (including road tax and registration) on total loss or theft | Essential for new cars up to 3 years old |
| Key & Lock Replacement | ₹200–₹400 fixed | Reimburses replacement cost for lost electronic smart keys and lock set reprogramming | Optional / Skippable (Unless key replacement costs exceed ₹15,000) |
| Daily Conveyance Allowance | 3%–5% | Pays a fixed daily cash stipend (₹500–₹1,000 per day) while your car is in the repair workshop | Skippable (If you have access to alternate personal or transit options) |
Popular Car Insurance Add Ons Worth It: Coverage & Limitations
Car insurance add-ons worth it primarily include Engine Protection, Zero Depreciation, and Return to Invoice covers. These are affordable and are meant to offer that extra financial protection that your regular policy misses out on. But these car insurance add-ons are not standalone policies. You must purchase them alongside a standard comprehensive or own damage policy.
Zero Depreciation Cover
A Zero Depreciation car insurance add-on ensures you get full claim coverage for replaced parts during accidental damage repairs without depreciation deductions.
- Depreciation Deductions: A standard policy without Zero Depreciation deducts 50% for replacing plastic bumpers, nylon, rubber seals, and airbags, and 30% for fibreglass components during an accident.
- Financial Coverage: A Zero Depreciation add-on waives depreciation deductions, so you only pay the mandatory deductible fee set by the insurer.
- Cost Efficiency: Insurers charge a slightly higher premium, roughly 10-20% of your regular comprehensive or own damage premium, due to the added benefit.
- Real-World Limitations: The add-on does not cover engine or mechanical failures and consumables.
Engine Protection
An Engine Protection add-on covers the replacement or repair costs for damage caused to the car’s engine and internal parts due to water ingress or oil leakage.
- Water Ingress Coverage: Covers damage if water enters the engine during heavy rainfall or waterlogging.
- Lubrication Failure Protection: Covers internal damage caused by engine oil leakage due to accidents.
- Cost Savings: Engine damage caused by hydrostatic lock typically costs between ₹1.5 lakh and ₹3.5 lakh, depending on the car model. By paying just 5-10% extra for an Engine Protection cover, you can save huge out-of-pocket expenses.
- Real-World Limitations: Insurers don’t cover expenses for driver’s negligence, such as when you keep cranking or restarting the ignition after water enters the engine.
Return to Invoice (RTI)
A Return to Invoice cover bridges the gap between the car’s IDV and the original invoice price after total loss, theft or irreversible damage.
- Protection Against Total Loss: While a standard policy pays only up to the vehicle’s Insured Declared Value (IDV) in case of theft or total loss, an RTI add-on covers the full original invoice price, including road taxes and registration charges.
- Full Refund Benefit: Covers the car’s original on-road price, which includes RTO charges, road taxes, and factory-fitted accessories.
- Best Suited For: New cars up to 3 years of age
- Real-World Limitations: An RTI cover generally does not apply to car models older than three years. Additionally, it does not pay for minor repairs, such as scratches or dents.
Car Insurance Add Ons You Can Skip to Lower Premiums
Not every add-on is essential for new car owners. Some simply increase your insurance premium without providing adequate financial protection. You can skip car insurance add-ons that are not worth buying, such as Daily Conveyance, Key and Lock Set Replacement, and Tyre and Rim Security cover.
- Daily Conveyance: This covers your daily transport costs while your car is sent for accidental repairs. The insurer pays a fixed amount, roughly between ₹500 and ₹1,000, to cover the conveyance expenses. If you own a secondary vehicle or depend on cab aggregators, you can skip this add-on and save 3-5% on your annual premiums.
- Key and Lock Set Replacement: This provides coverage for lost key and lock replacement up to ₹10,000. Paying a higher premium for this add-on makes sense only if you use a specialized high-security key fob costing more than the coverage limit.
- Tyre and Rim Security: This covers discrete tyre cuts or bulges, excluding routine wear and tear. This makes it unnecessary for low-mileage drivers who mainly commute within the city.
The smartest way to build a cost-effective policy is to compare car insurance add-ons worth it, check the inclusions and exclusions, the percentage of your annual premium, deductibles, and evaluate your own requirements.
If you are a first-time buyer, adding a Zero Depreciation add-on to your existing comprehensive or own damage policy is a no-brainer. Engine Protection is highly recommended for drivers in a flood-prone region. Finally, for owners concerned about the gap between IDV and replacement costs, an RTI cover is worth considering.
FAQs
What is the difference between IDV and RTI?
Insured Declared Value (IDV) is the maximum sum an insurer pays if your vehicle is stolen or suffers a total loss. Because IDV is calculated by subtracting depreciation from the vehicle’s ex-showroom price, it does not cover the full original cost. Return to Invoice (RTI) fills this gap by allowing you to recover the original invoice price, including registration charges and road taxes.
Can I add insurance riders in the middle of my policy tenure?
No, you can purchase car insurance add-ons worth it only when buying a new policy or renewing an existing one at the end of its annual term.
Is Return to Invoice better than comprehensive insurance?
A Return to Invoice is an add-on cover, not a standalone insurance policy. It extends coverage of the base comprehensive or own damage car insurance policy rather than replace it.
Is engine protection add-on necessary for every car?
No, an engine protection add-on cover is most suitable for cars operating in flood-prone areas where the risk of engine and gearbox damage is high. It is important to check the policy inclusions and conditions before purchasing.
Should I skip the Key Replacement add-on?
You can skip the key replacement add-on if you are driving an old car model which has a mechanical key without an electronic chip or immobilizer. Replacing the key and lock in such cases is not that expensive and does not require an insurance rider.